
Home › Industry News
OAG: SE Asia capacity lags in recovery levels
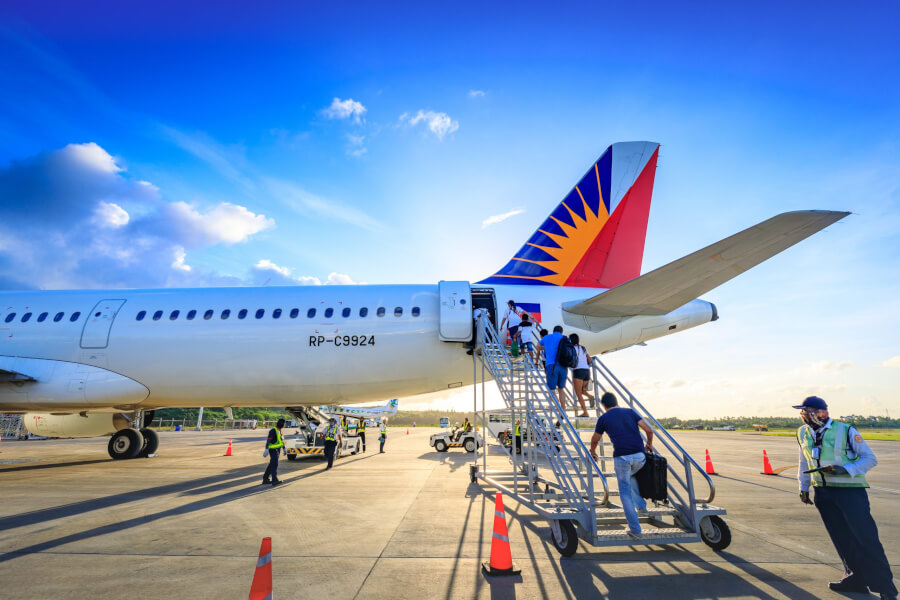
In a new comparison of airline capacity data aviation data provider OAG highlights the regions and countries where airline capacity is growing and contracting, as well as the areas still waiting to resume normal levels post-pandemic. By the end of this year, four regional aviation markets will still not have returned to their 2019 capacity levels. These are: Southeast Asia (-13.1%) Eastern Europe (-8.6%) Southern Africa (-17.0%) Southwest Pacific (-4.5%) In Southeast Asia the much-discussed Chinese international market recovery lingers, while in Eastern Europe the ongoing situation in Ukraine continues to affect capacity, although there has been growth this year. Southern Africa has seen the loss of two of its largest airlines and in the Southwest Pacific, modest capacity cuts versus 2019 from a range of airlines continue to draw back capacity growth. A year-on-year comparison (2024 to 2023) shows there are just two regions not recording capacity growth: Central America (-0.7%) and Central/Western Africa (-1.9%). Across the 20 largest country markets in the world half have yet to recover back to 2019 capacity levels as a combination of geo-political circumstances, aviation taxes, and sustainability pressures impact operations. However, all but Mexico (-3.3%) have grown capacity when compared to 2023. Standout growth markets include the United Arab Emirates with 15.0% more capacity than in 2019 and 10.5% capacity growth year on year, and India, where capacity is 12.7% higher than in 2019 and has grown 8.0% this year compared to last. Spain is now the largest European market as 9.4% growth in 2024 has nudged them ahead of the United Kingdom. Globally, there has been 6.4% capacity growth year-on-year, but with the two major manufacturers likely to deliver around 30% fewer new aircraft than hoped, aircraft grounded due to engine reliability problems (Indigo Airlines, for example, currently have around 68,000 “lost” seats per day due to aircraft out of action), and ongoing skill shortages, this growth could have been significantly higher. John Grant, OAG’s Chief Analyst, comments: “There are clear signs that demand is coming slightly off the boil of post pandemic revenge spending. While the appetite for air travel remains, economic pressures such as the cost of living, increasing taxation and the constant spectre of geo-political events will leave most airline and airport CEOs on high alert for what’s next.“ For Editorial Inquiries Contact: Editor Matt Driskill at [email protected] For Advertising Inquiries Contact: Head of Sales Kay Rolland at [email protected]
TAGSOAG
Previous article
GE Aerospace, Boeing and NASA eyeing Open Fan engine design
Matt Driskillhttp://www.matt-driskill.com
Matt Driskill is the Editor of Asian Aviation. He has been an Asia-based journalist and content producer since 1990 for outlets including Reuters and the International Herald Tribune/New York Times and is a former president of the Foreign Correspondents Club of Hong Kong. He appears on international broadcast outlets like Al Jazeera, CNA and the BBC and has taught journalism at Hong Kong University and American University of Paris. In 2022 Driskill received the “Outstanding Achievement Award” from the Aerospace Media Awards Asia organisation for his editorials and in 2024 received a “Special Recognition for Editorial Perspectives” award from the same organisation. Driskill has received awards from the Associated Press for Investigative Reporting and Business Writing and in 1989 was named the John J. McCloy Fellow by the Graduate School of Journalism at Columbia University in New York where he earned his Master's Degree.
马特·德里斯基尔(Matt Driskill)是《亚洲航空》(Asian Aviation)的主编。他自1990年起,担任驻亚洲的记者和内容制作人,曾为路透社、国际先驱论坛报/纽约时报等媒体工作,并曾任香港外国记者协会会长。他也曾多次在半岛电视台、新加坡广播公司(CNA)和BBC等国际媒体担任嘉宾,并在香港大学和巴黎美国大学教授新闻学。2022年,德里斯基尔因其评论获得了航空媒体奖(Aerospace Media Awards Asia)颁发的“杰出成就奖”,2024年又因其编辑观点获得同一组织颁发的“特别表彰”。他曾获得美联社的调查报道和商务写作奖,并于1989年被纽约哥伦比亚大学研究生新闻学院授予约翰·J·麦克劳伊学者(John J. McCloy Fellow)称号,获得硕士学位。